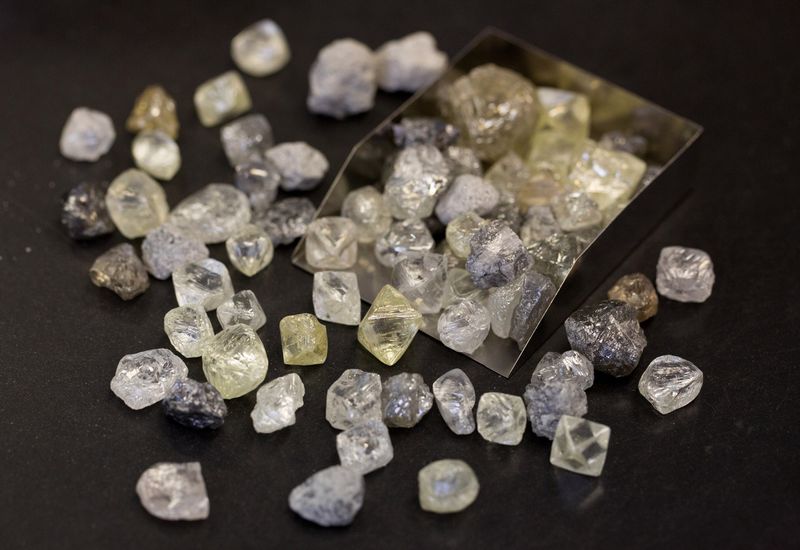

ZIMBABWE’s diamond sector is facing a severe economic squeeze, earning US$62.3 million from diamond exports between January and September 2026.
According to the latest trade data, the country sold 2.52 million carats during this nine-month period, but a steep decline in global and local realised values continues to heavily weigh on the industry’s total revenue.
The industry is currently grappling with a sharp drop in market value, with diamonds fetching an average of approximately US$24.72 per carat.
This figure represents a major decline from recent years, including the full-year 2025 average of US$27.16 and the highs of US$53.18 per carat recorded in 2023.
This price collapse has heavily offset aggressive domestic efforts to ramp up production and improve local processing capabilities.
This downturn highlights a stark divergence within Zimbabwe’s broader mining sector, which has otherwise enjoyed a massive export boom.
Led by record-breaking gains in gold and lithium, the country’s total mineral export earnings surged past US$4.73 billion in the first nine months of the year.
In sharp contrast, diamond revenues contracted by nearly 46.6% in the first seven months of 2026 compared to the same period in 2025, underscoring the unique and isolating pressures facing local gemstone producers.
Industry experts point to a combination of internal geological shifts and external global pressures as the primary drivers of the crisis.
On the domestic front, the easily accessible surface alluvial diamond deposits in the famous Marange fields have been largely depleted.
This has forced major producers, including the state-backed Zimbabwe Consolidated Diamond Company (ZCDC), to transition to deeper and more expensive conglomerate ore extraction.
At the same time, the global market offers little relief. Natural diamond prices worldwide remain under intense downward pressure due to changing consumer habits, weakened demand in key international cutting and polishing hubs, and rapid market penetration by cheaper lab-grown synthetic alternatives.
In response to these headwinds, Zimbabwean mining firms have aggressively pushed forward with infrastructural expansions to stabilize the sector.
Substantial capital has been channeled into upgrading recovery infrastructure, including the targeted completion of the major Area 3 diamond plant expansion in Chiadzwa.
However, while these initiatives have succeeded in keeping production volumes steady, the sheer scale of the global price slump means that processing more rock has simply not been enough to rescue the country’s overall diamond balance sheet.